Muscat: The Reserve Bank of India’s (RBI) 25 basis points repo rate hike to 5.50 per cent is set to have a mixed impact on Non Resident Indians (NRIs) —loan EMIs could become costlier, while their deposits may earn better.
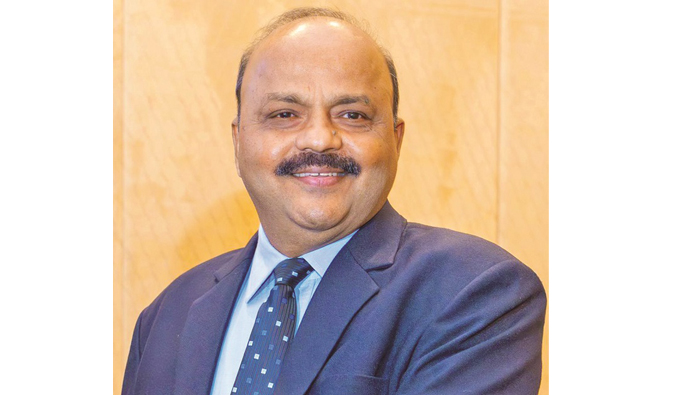
Speaking to Times of Oman, R. Madhusoodanan, former SBI official and Muscat-based financial expert, said the rate hike was widely expected. The hike marks the first increase in the repo rate since February 2023., a gap of almost 4 years. The RBI has also shifted its policy stance from neutral to “calibrated tightening.”
Indian banks could raise lending rates following the RBI’s repo rate increase. NRIs who have taken housing, vehicle, mortgage, personal or other floating-rate loans in India could therefore see their equated monthly instalments (EMIs) rise as lenders transmit the higher policy rate to borrowers.
“For a housing loan of ₹50 lakh with a tenure of 25 years, the additional monthly burden could be around ₹800, depending on the existing interest rate and the extent of transmission by the lending institution,”
While the increase in the monthly EMI may appear modest, the cumulative impact over the remaining tenure of a long-term loan can be significant. Borrowers, particularly NRIs servicing Indian loans from overseas, should ensure that the revised EMIs are paid promptly.
Failure to service the revised EMI could result in the loan account becoming irregular. This may attract penal charges and, if the account remains overdue, could eventually affect the borrower’s credit profile and result in the account being classified as a non-performing asset (NPA).
The rate hike is also likely to increase the cost of borrowing for businesses. Higher interest expenses on working capital and other business loans could put pressure on their profit margins.
Businesses may seek to offset higher financing costs by raising prices of goods and services thereby passing the burden on consumers. At the same time, higher borrowing costs could moderate consumption and investment, potentially slowing the pace of economic activity.
The RBI’s real GDP growth of 7.6 percent projected for 2026-27, will therefore remain an important factor in assessing the broader important.
The rate increase, however, has a positive side for depositors, including NRIs. Banks may also raise deposit rates and the extent may differ from banks to banks. This will be a huge relief to the senior citizens, pensioners and others who depend on interest income.
However the higher rate will be applicable to fresh deposits and for those maturing. The existing deposits will carry the contracted rate till their maturity. All fixed income investments will also benefit out of this hike.
The RBI’s shift in stance to “calibrated tightening” also assumes significance. RBI stance says future rate cuts are off the table. Though the rate hike was expected, the shift in the stance was unexpected. The future trajectory of interest rates will depend on a range of domestic and global factors, including inflation, crude oil prices, global interest-rate movements, currency fluctuations and international economic developments.
Both the stock market and the forex market have not reacted positively to the RBI’s policy. The Indian rupee nosedived to an intraday low of ₹96.91 against the US dollar, despite the RBI’s hawkish stance.
For NRIs, the rate hike therefore presents a mixed picture, with higher repayment obligations on loans on the one hand and the possibility of improved returns on rupee deposits on the other. Borrowers should ensure that revised EMIs are serviced promptly to avoid penal charges, account irregularities and potential damage to their credit profile, R. Madhusoodanan said.